A subvention scheme is not always a bad trade, but it carries a hidden risk that the buyer, not the builder, ends up holding.
Imagine walking past a big hoarding near the highway: “Book your dream flat today. Pay just 20% now, no EMI till possession!” It sounds like a gift. Someone else seems to pay your loan while your home is being built. This blog explains how such offers work, why they tempt buyers, and why many families in India regretted them.
What is a subvention scheme?
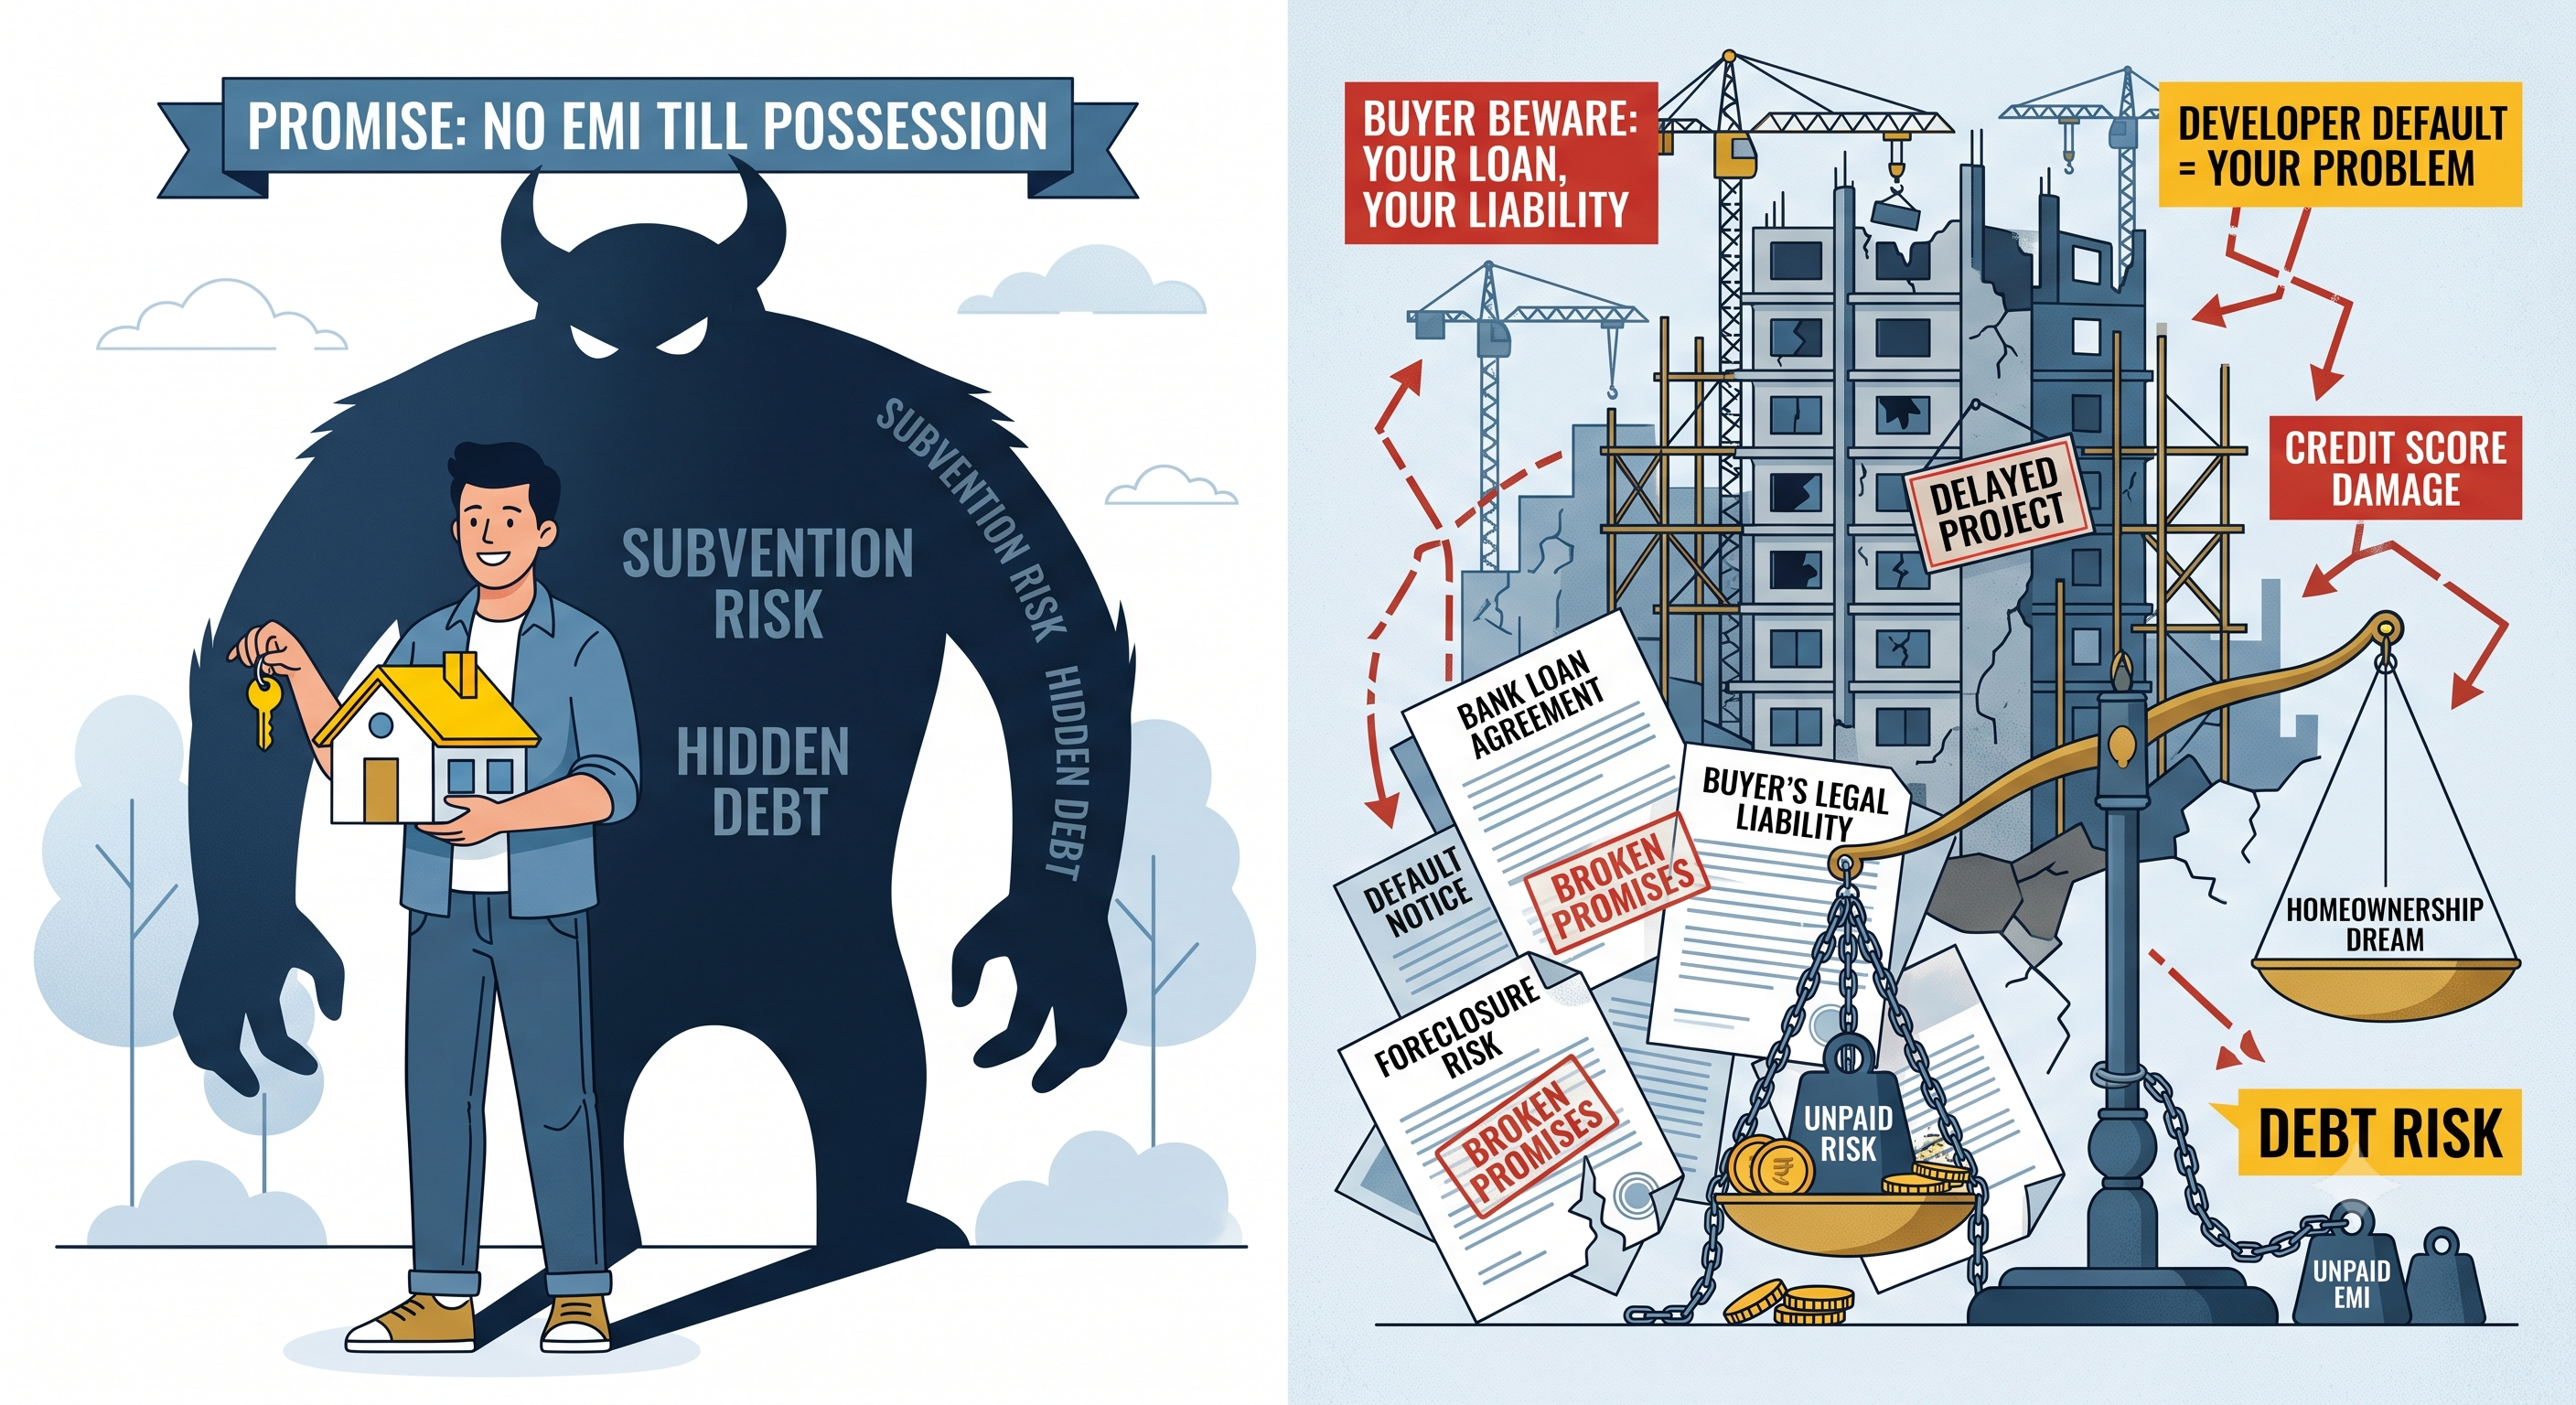
A subvention scheme is a deal where the seller pays the interest on your loan for a fixed period, so you pay little or nothing at first. “Subvention” simply means a subsidy or support payment.
In Indian real estate, the most famous version was the 80:20 scheme. The buyer paid 20% of the flat’s price upfront. A bank lent the remaining 80%, and the builder promised to pay the interest (the pre-EMI) until the flat was handed over. The same idea appears in “no-cost EMI” offers on phones, bikes and cars, where the shop or brand covers the interest.
How it works?
Let us follow Riya’s family as they buy an under-construction flat priced at ₹50 lakh. All numbers are rounded for easy maths.
- Down payment:The family pays 20%, which is ₹10 lakh.
- Home loan:A bank sanctions ₹40 lakh in the family’s name, at about 9% interest a year.
- Money goes to the builder:Under many subvention deals, the bank released most of the loan to the builder early, even though construction had barely started.
- Builder pays interest:Interest on ₹40 lakh at 9% is about ₹3.6 lakh a year, roughly ₹30,000 a month. The builder promises to pay this until possession, say 3 years.
- Possession:When the flat is ready, the family starts paying the full EMI themselves.
Notice the key detail: the loan is in the buyer’s name, but the promise to pay interest comes from the builder. If the builder stops paying, the bank asks the buyer.
Why it looks so attractive
The offer shifts the pain of paying into the future, and our brains love that.
- Small upfront cost:You “own” a ₹50 lakh flat for just ₹10 lakh today.
- No double burden:Families living on rent don’t pay rent and EMI at the same time.
- Investor dream:Some buyers planned to sell the flat before possession at a higher price, earning a profit without ever paying an EMI.
- Builder benefit:The builder gets a large amount of cash early to fund construction, without borrowing at high rates.
When property prices are rising quickly, everyone seems to win. The trouble starts when they don’t.
The Hidden Risks
The biggest risk is that the buyer carries the full loan while depending on the builder’s promise.
- Builder stops paying interest:If the builder runs short of cash, the bank turns to the borrower. Riya’s family would suddenly owe about ₹30,000 a month for a flat they cannot live in.
- Project gets delayed or stuck:Since the bank paid the builder early, there is little pressure to finish on time. Some buyers waited years for flats that never came.
- Hidden cost in the price:“Free” interest is rarely free. Builders often add it to the flat’s price, so you may pay more than a buyer who chose a normal plan.
- Credit score damage:Missed EMIs, even ones the builder was supposed to pay, show up on the buyer’s credit report and can hurt future loans.
- Rent plus EMI:Families still living on rent can end up paying both, the exact problem the scheme promised to avoid.
The real-world lesson from India
This is not just theory. During the slowdown of the 2010s, many builders, especially around Delhi-NCR and Mumbai, stopped paying the interest they had promised. Thousands of homebuyers received loan-recovery notices for incomplete flats. Regulators stepped in: the RBI told banks back in 2013 not to release loans to builders ahead of construction progress, and in 2019 the National Housing Bank asked housing finance companies to stop such subvention schemes. Cases from affected buyers have since reached the Supreme Court.
So, is it a bad trade?
It depends on who stands behind the promise: with a strong, trusted seller it can be fine; with a weak one, it is a risky bet with your money.
Usually a fair deal | Usually a bad trade |
Large, well-known builder with a clean delivery record | New or cash-strapped builder with delayed past projects |
Small purchases like a phone on “no-cost EMI” | A home loan worth lakhs, stretched over years |
Loan released only as construction progresses | Bank pays the builder most of the money upfront |
You could pay the EMI yourself if needed | You are counting on the builder to pay |
Before saying yes to any “pay later” offer, a smart investor asks:
- Is the project registered under RERA, and is it on schedule?
- What is the price without the scheme? Is the interest hidden inside?
- Is the promise to pay interest written in a three-way agreement between me, the builder and the bank?
- Can I afford the full EMI on my own if the builder stops paying?
Key takeaways
- A subvention scheme lets the seller pay your loan interest for a while, so you pay less at the start.
- The loan is still in your name. If the seller fails, you pay.
- “Free” interest is often built into a higher price.
- India’s 80:20 housing schemes hurt many families, which is why regulators restricted them.
- Golden rule for any investor: never take a deal you couldn’t survive if the other side broke its promise.