
1.1 What Financial Sovereignty Means
What Financial Sovereignty Means
Personal finance is often thought of as something related to balance sheets, ratios and complex formulas.. In reality personal finance is about freedom, dignity and control over your life choices. The numbers are tools. The true purpose of finance is to give you the power to live life on your terms. Financial sovereignty means reaching a point where money no longer makes your decisions for you. It is not about luxury items or expensive assets. It is about owning your time and your freedom.
Key Advantages of Financial Sovereignty
- Freedom from work: You can walk away from a job that’s not good for you without worrying about financial ruin.
- Time with family: You can spend time with your loved ones without being stressed about money.
- Independent decision making: Your life choices. Like education, career or lifestyle. Are based on your values not on how money you have.
- Peace of mind: When you have security stress fades. You are free to focus on growth, happiness and living
Why Personal Finance Has to Be Personal
Every family has obligations, values and risk tolerances. Some financial product sellers or advisors who earn commissions may push products that benefit them more than they benefit you. A smart way to protect yourself is to invest through plans that do not carry distributor commissions.. You can get advice from a SEBI-registered investment adviser (RIA) who charges a fee instead of earning commissions.
Conflicts of interest: Your advisor’s goals may not match your goals.
- Your own risk tolerance: You know how uncertainty you and your family can handle.
- Family obligations: The needs for education health care and retirement differ from one family to another.
- Simplicity: You don’t need to be a math expert to manage your money. Simple arithmetic is often enough.
Finance as Empowerment
Think of finance not as a subject but as a source of power. Just as learning opens the mind personal finance knowledge opens your options. It helps you avoid falling into cycles of debt. It helps you stop making decisions just to survive.
उदाहरण
Imagine a middle-class family:
A father works in a job. A mother manages home life and teaches part-time. Their children want to pursue education. If this family reaches sovereignty: The father can leave a harmful work environment. The mother can focus on her passions and interests. The children can pursue their education without fear of money problems. This is not about having a lot of money. It is, about having the freedom to choose.
1.2 The Silent Destroyer: The Cost of Waiting
A obstacle to building wealth is the belief that small amounts of money are not worth investing. I notice that waiting is the Silent Destroyer. If you wait a years to start you could lose a large amount of money that you would have earned otherwise. This is due to compounding – the way your money earns returns on the returns it has earned before over time. Waiting is the Silent Destroyer: it quietly erodes the wealth you could have built.
Case Study: Ravi, Meera and Arjun
Each invests ₹5,000 per month in an equity fund that earns a nominal 12% a year compounded monthly (1% per month which is about 12.7% per year). This rate is an assumption for illustration; equity returns are not guaranteed and can change each year. All figures are before fund expenses and taxes: expense ratios cut returns. Under current rules longterm gains on equity funds above ₹1.25 lakh a year are taxed at 12.5% so actual outcomes will be lower. Let’s see how their wealth grows each year until age 60.
Calculation Methodology & Formula
Contribution (P): ₹5,000
वार्षिक रिटर्न: 12% per year (nominal) compounded monthly (i = 1% = 0.01 per month; effective annual rate ≈ 12.68%)
SIP Formula (During Investment Years):
where M = maturity value (corpus) P = monthly contribution, n = number of monthly installments and i = 1% = 0.01 per month
Lump-Sum Formula (During Holding Years After Contributions Stop):
A = C × (1 + i)m where C = corpus built up when contributions stop i = 1% = 0.01, per month and m = number of months the money stays invested
Complete Year by Year Corpus Table
(L = lakh, Cr = crore)
|
वय |
Ravi (Invests 22–31, then stops) |
Meera (Invests 32–60, 29 years) |
Arjun (Invests 40–60, 21 years) |
|
22 |
₹0.64 एल |
— |
— |
|
23 |
₹1.36 एल |
— |
— |
|
24 |
₹2.18 एल |
— |
— |
|
25 |
₹3.09 एल |
— |
— |
|
26 |
₹4.12 एल |
— |
— |
|
27 |
₹5.29 एल |
— |
— |
|
28 |
₹6.60 एल |
— |
— |
|
29 |
₹8.08 एल |
— |
— |
|
30 |
₹9.74 एल |
— |
— |
|
31 |
₹11.62 एल (stops investing) |
— |
— |
|
32 |
₹13.09 एल |
₹0.64 एल |
— |
|
33 |
₹14.75 एल |
₹1.36 एल |
— |
|
34 |
₹16.62 एल |
₹2.18 एल |
— |
|
35 |
₹18.73 एल |
₹3.09 एल |
— |
|
36 |
₹21.10 एल |
₹4.12 एल |
— |
|
37 |
₹23.78 एल |
₹5.29 एल |
— |
|
38 |
₹26.80 एल |
₹6.60 एल |
— |
|
39 |
₹30.20 एल |
₹8.08 एल |
— |
|
40 |
₹34.03 एल |
₹9.74 एल |
₹0.64 एल |
|
41 |
₹38.34 एल |
₹11.62 एल |
₹1.36 एल |
|
42 |
₹43.20 एल |
₹13.73 एल |
₹2.18 एल |
|
43 |
₹48.68 एल |
₹16.11 एल |
₹3.09 एल |
|
44 |
₹54.86 एल |
₹18.80 एल |
₹4.12 एल |
|
45 |
₹61.81 एल |
₹21.82 एल |
₹5.29 एल |
|
46 |
₹69.65 एल |
₹25.23 एल |
₹6.60 एल |
|
47 |
₹78.49 एल |
₹29.07 एल |
₹8.08 एल |
|
48 |
₹88.44 एल |
₹33.40 एल |
₹9.74 एल |
|
49 |
₹99.66 एल |
₹38.27 एल |
₹11.62 एल |
|
50 |
₹ 1.12 कोटी |
₹43.77 एल |
₹13.73 एल |
|
51 |
₹ 1.27 कोटी |
₹49.96 एल |
₹16.11 एल |
|
52 |
₹ 1.43 कोटी |
₹56.93 एल |
₹18.80 एल |
|
53 |
₹ 1.61 कोटी |
₹64.79 एल |
₹21.82 एल |
|
54 |
₹ 1.81 कोटी |
₹73.65 एल |
₹25.23 एल |
|
55 |
₹ 2.04 कोटी |
₹83.63 एल |
₹29.07 एल |
|
56 |
₹ 2.30 कोटी |
₹94.88 एल |
₹33.40 एल |
|
57 |
₹ 2.59 कोटी |
₹ 1.08 कोटी |
₹38.27 एल |
|
58 |
₹ 2.92 कोटी |
₹ 1.22 कोटी |
₹43.77 एल |
|
59 |
₹ 3.29 कोटी |
₹ 1.38 कोटी |
₹49.96 एल |
|
60 |
₹ 3.71 कोटी |
₹ 1.56 कोटी |
₹56.93 एल |
Key Summary of Results
– Ravi invested a total of ₹6.00 lakh over 10 years (ages 22–31). Final corpus at age 60 equals ₹3.71 crore.
– Meera invested a total of ₹17.40 lakh over 29 years (ages 32–60). Final corpus at age 60 equals ₹1.56 crore.
– Arjun invested a total of ₹12.60 lakh over 21 years (ages 40–60). Final corpus at age 60 equals ₹56.93 lakh.
मुख्य धडे
- Start early: Ravi invested less but ended with the wealth.
- Delay is costly: Meera invested nearly three times as much as Ravi but ended with less than half of Ravi’s corpus.
- Late starts cost the most: Arjun invested than twice as much as Ravi but ended with less, than one-sixth of Ravi’s corpus.
1.3. Behavioral Finance: Why Behavior Beats Brains
Financial success is not about being the smartest person in the room or having insider knowledge of the stock market. It is about behavior—the way you manage emotions, practice discipline, and stay consistent over decades. As Morgan Housel puts it in The Psychology of Money, “Doing well with money has a little to do with how smart you are and a lot to do with how you behave.”
Watch the full video here: https://www.youtube.com/watch?v=52vKmgajlXM.
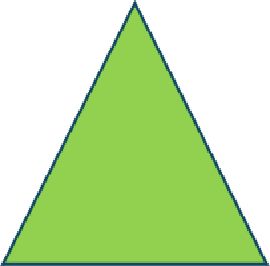
The Wealth Triangle
Think of wealth creation as a triangle with three sides:
- वेळ: The longer your money stays invested, the more compounding works in your favor.
- शिस्त: Staying consistent with savings and resisting the temptation to withdraw or overspend.
- कम्पाउंडिंग: The result that time and discipline produce together—the silent force that multiplies your wealth.
The Wealth Triangle
वेळ
DISCIPLINE COMPOUNDING
Key Behavioral Lessons
- Patience Over Action
- True wealth is not created by constant trading or speculation. It grows silently when you wait and allow compounding to do its work.
- Example: An investor who stays invested in a mutual fund SIP for 25 years will likely outperform someone who switches funds every year chasing “hot tips.”
- Wealth Is What You Don’t See
- Wealth is not the flashy car or the big house. It is the unspent capital—the savings, investments, and emergency funds quietly growing in the background.
- Example: A person with ₹50 lakh in mutual funds and fixed deposits may look “ordinary” compared to someone driving a luxury car. But the first person has true wealth, while the second may only have debt.
- The Inflation Reality Check
- Always measure returns in real terms. If your portfolio grows at 12% annually but your lifestyle costs rise at 6% (a cautious long-term assumption for household costs; India’s headline CPI inflation has been lower recently, roughly 3–4.5% in 2026), your real purchasing power is increasing by only a little under 6% a year (about 5.7%).
- Example: If your savings of ₹1 lakh grow to ₹2 lakh in 12 years, but prices also double in that time (which is roughly what 6% inflation does over 12 years), your purchasing power has not improved at all.
1.4. Action Plan: Immediate Next Steps
To build wealth, you need to move from theory to practical systems. Execution is what separates dreaming about financial freedom from actually achieving it. Let’s walk through three steps using the example of a young professional in India.
Riya, 24, Bengaluru, IT professional.
Riya earns a monthly salary of ₹35,000. She feels her salary is modest and wonders whether she should wait for a raise before investing. Rather than waiting, she follows a three-step action plan.
Step 1: Start Small, Today
Riya starts a monthly SIP of ₹2,000 in an equity mutual fund. The habit, not the number, is what matters: many funds now accept SIPs from as little as ₹250 under SEBI’s “Chhoti SIP” initiative, and some from ₹100, so even a smaller start is worth making. She can increase the amount as her salary grows.
- 20-Year Horizon:A ₹2,000 monthly SIP at 12% p.a. grows to ~₹20 lakh in 20 years (at age 44).
Step 2: Automate It All
Riya sets up an auto-debit on the 1st of every month. This ensures disciplined investing before discretionary spending takes over.
- Progress Milestones (₹2,000/month at 12% p.a.):
- 10 Years (Age 34):~₹ 4.7 लाख
- 15 Years (Age 39):~₹ 10.1 लाख
- 20 Years (Age 44):~₹ 20.0 लाख
Step 3: Review Expenses & Accelerate
Expense Leak Calculation:
- Daily Coffee: ₹150/day × 30 days = ₹4,500/month
- Inactive Subscriptions: ₹1,000/month
- Impulse Online Purchases: ₹2,000/month
- Total Monthly Leaks:₹4,500 + ₹1,000 + ₹2,000 = ₹7,500/month
- Redirecting 50% of Leaks:₹7,500 / 2 = ₹3,750/month into an additional SIP.
Aligning Time Horizons to Age 44 (20-Year Timeline)
Both SIPs run simultaneously over Riya’s 20-year horizon (age 24 to 44, i.e. 240 months):
- Original SIP (₹2,000/month for 20 years):~₹ 19.98 लाख
- Expense Leak SIP (₹3,750/month for 20 years):~₹ 37.47 लाख
- Combined Total Corpus at Age 44:₹19.98 lakh + ₹37.47 lakh = ₹ 57.45 लाख


