2.1 What Is An NFO?
Anand: Ridhima, what’s an NFO?
Ridhima: It’s a New Fund Offer. A mutual fund company launches a new scheme, and investors can buy units—usually at ₹10 each. For example, SBI launched the Energy Opportunities Fund in February 2024.
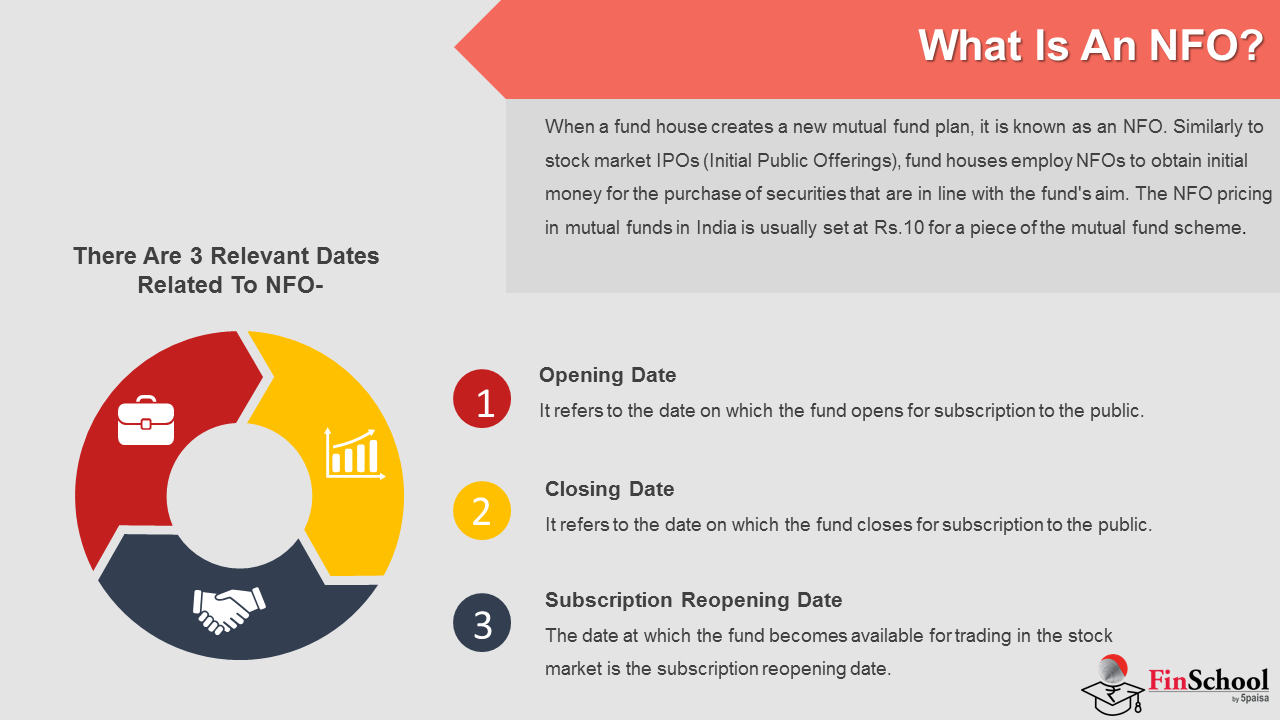
A New Fund Offer or NFO is when a mutual fund company launches a fund. It is like when a company issues shares to the public for the first time (an IPO). Instead of buying stocks you buy units of a mutual fund. In India, NFOs are usually priced at ten rupees per unit. After the NFO closes and units are allotted, an open-ended scheme reopens for regular buying and selling (within five business days of allotment). Then you can buy units at a price (NAV) that changes every day.
Example: In February 2024 (6th to 20th February) SBI Mutual Fund launched the SBI Energy Opportunities Fund as an NFO. It focuses on companies in traditional and new energy. Investors could buy units for ten rupees, with a minimum investment of ₹5,000.
Anand: How do people invest in NFOs?
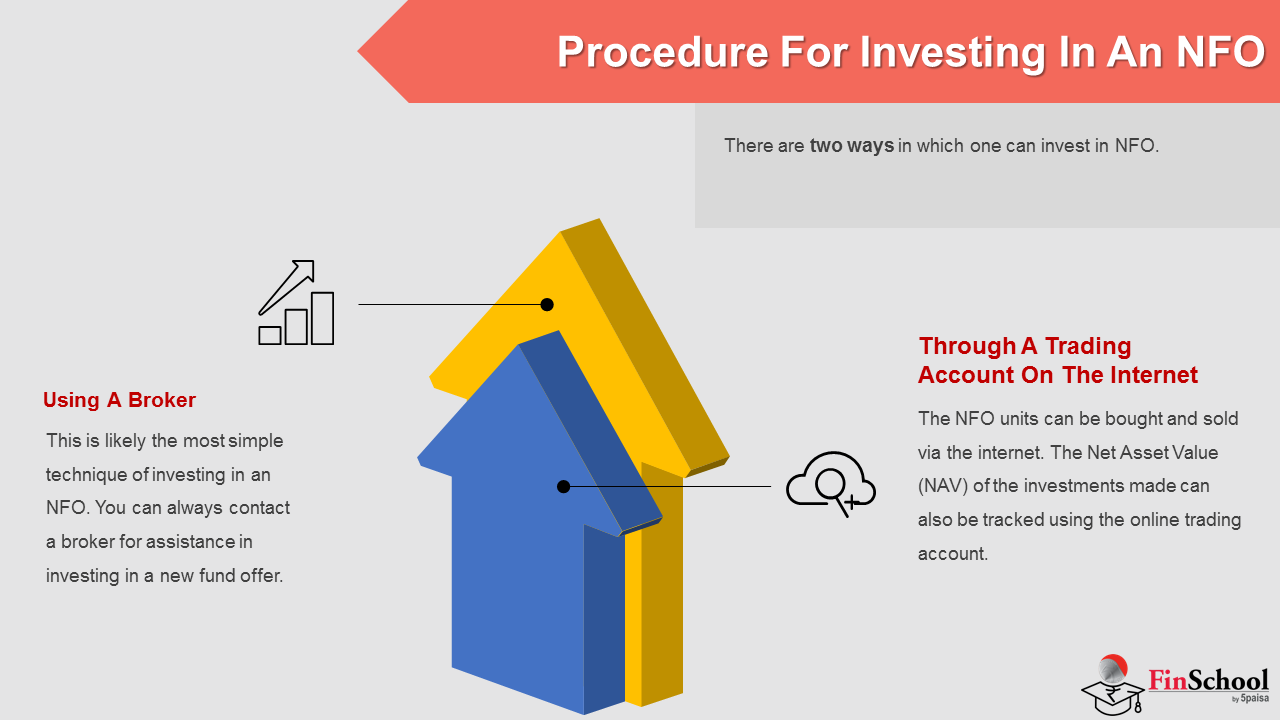
Ridhima: Two ways:
- Through brokers or distributors, who help with paperwork and guidance but are paid a commission through the scheme’s Regular Plan, which has a higher expense ratio.
- Via online platforms, which are faster, paperless, and give you control over your investments. Buying the Direct Plan (on the AMC website or a direct platform) is cheaper.
Type of NFO
Open-ended vs close-ended: Not all NFOs behave the same way after they close. In an open-ended fund, you can buy and redeem units with the fund house on any business day once the scheme reopens. A close-ended fund, such as an FMP or some thematic funds, locks your money in for a fixed tenure. During that time you can only sell your units on the stock exchange where they are listed, sometimes at a discount to NAV.
Why ₹10 is not a “discount”: A common myth is that ₹10 is cheap compared with an existing fund whose NAV is ₹150. It isn’t. ₹10 is only the starting price. What matters is how the fund’s investments perform from that point, not the price at which you enter.
Anand: So once the NFO starts, what dates should I watch?
Ridhima: There are four.
- Opening Date:The day the NFO opens for subscription.
- Closing Date:The last day to subscribe at the ₹10 offer price. An NFO can stay open for at most 15 days, except ELSS.
- Allotment Date:The day units are credited to investors, within 5 business days of the closing date. Any lock-in, such as the 3-year ELSS lock-in, is counted from this date.
- Reopening Date:for open-ended schemes, the day the fund reopens for regular buying and redemption at the daily NAV, within 5 business days of allotment. Close-ended schemes are listed on a stock exchange instead and do not reopen with the fund house.
Between the closing date and the reopening date, investors cannot buy or redeem units. The reopening date is when the fund effectively “goes live” for new investors, who from then on buy at the daily NAV rather than at the ₹10 offer price.
2.2 Procedure For Investing In An NFO
Through a Broker
Brokerage houses facilitate an investor’s participation in a mutual fund scheme, and several investors prefer this route as it offers them guidance and support.
- Support: The broker usually assists the investor in filling the forms accurately and guides them through the compliance procedures.
- Convenience: The broker often comes to the investor’s office or home to collect the necessary documents and signatures. Trust Some investors feel reassured by having a trusted person walking them through the process.
- Cost : However, a broker might charge commissions from the investor, which could cut into the overall returns of the mutual fund scheme; nevertheless, several investors remain willing to pay extra to get the guidance of a trusted mutual fund advisor.
Via Online Platforms
Mutual fund investors these days can easily get access to an NFO via digital platforms, which has significantly simplified the subscription process.
- Accessibility : The digital platform provides a convenient option for the investor to sign up for an NFO. Speed The entire process is quick and only takes a few minutes to complete.
- Paperwork: The online portal assists the investor in completing the application process without any hassles.
- Information : An online portal provides the information an investor needs to make an informed decision about their investment.
- Cost-effectiveness : The investor can save on brokerage charges by eliminating the need for a mutual fund advisor. Control An investor who prefers to deal directly with their investments can conveniently do so.
Anand: What should I check before investing in an NFO?
Ridhima: Look into the fund house’s credibility, the objectives and risks of the scheme, the lock in period, the subscription amount, the expenses and if the theme appealed to you.
2.3 Points To Consider While Investing In New Fund Offer
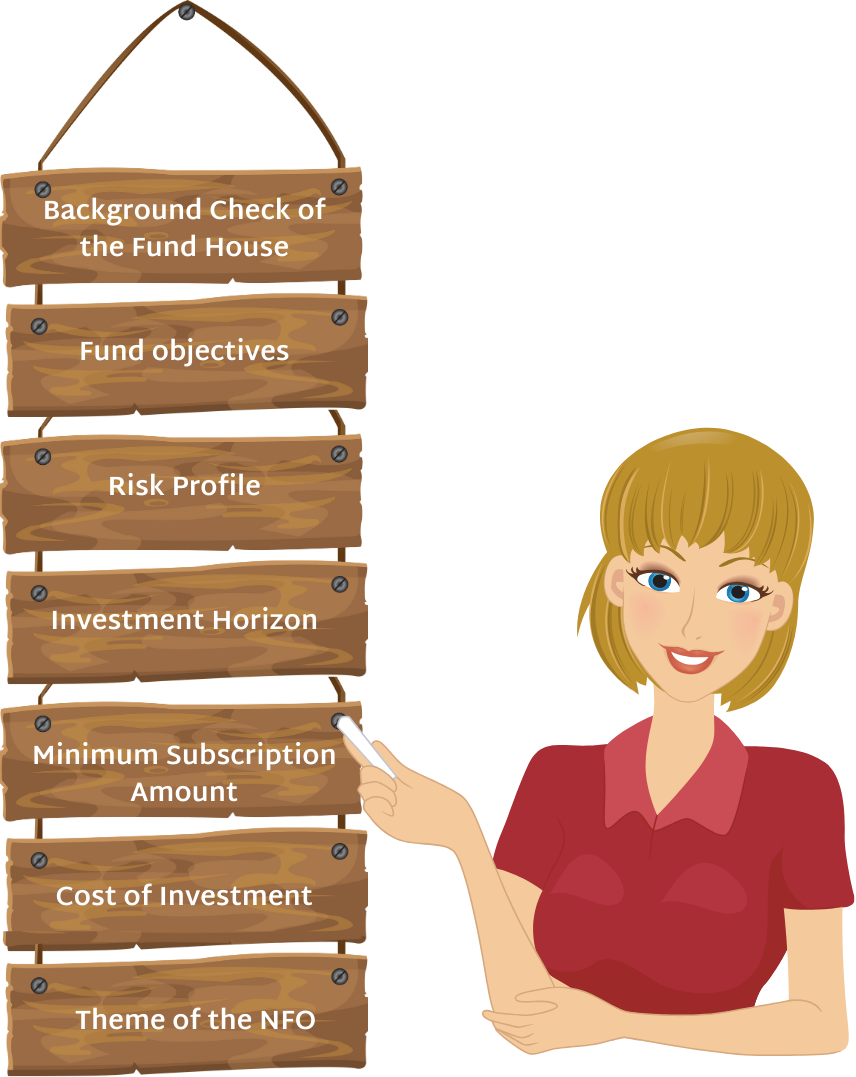
Anand: Okay, so before I put money into any NFO, what should I actually be checking?
Ridhima: Good instinct — since an NFO has no track record, you’re evaluating it almost entirely on paper. Let me go through each factor in depth.
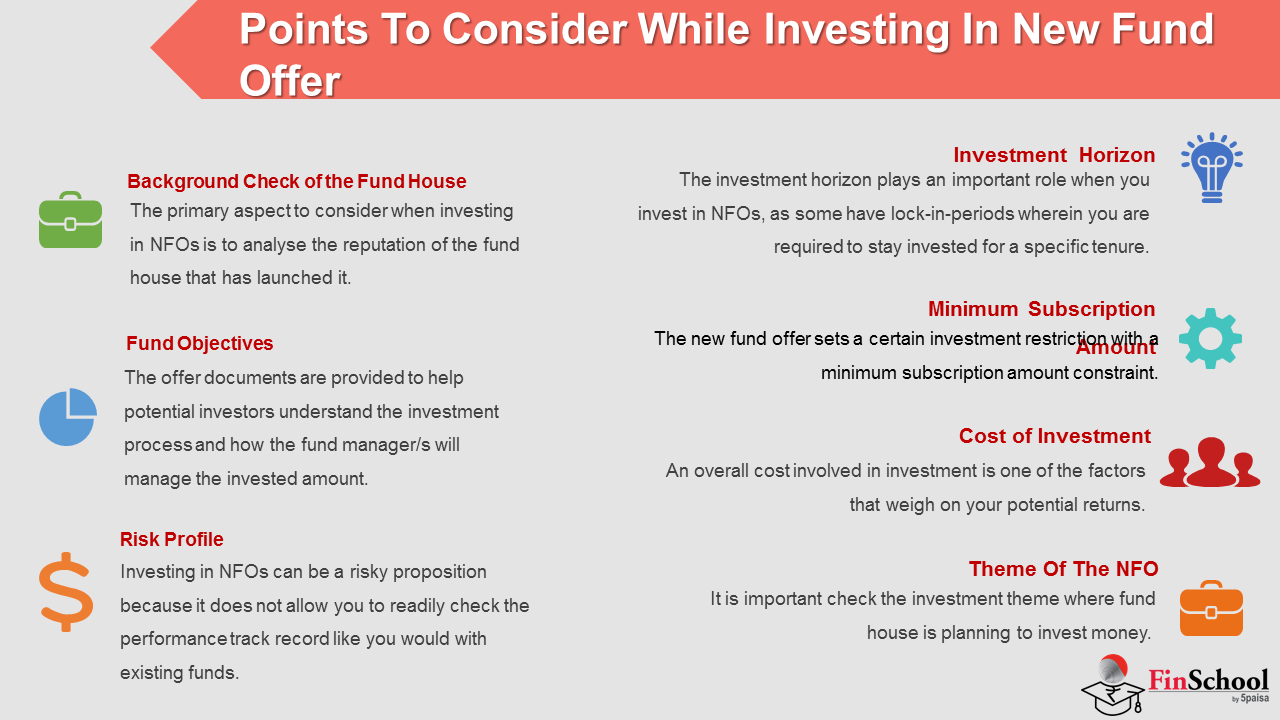
1. Fund House Reputation
You’re trusting the fund house with your money before the scheme itself has proven anything, so their overall track record matters a lot.
- Look at how their existing schemes have performed over 5–10 years, across market cycles (not just in a bull run).
- Check their AUM (assets under management) size and stability — a house that’s seen consistent inflows tends to be more trusted by other investors too.
- Look at the fund management team’s experience and how long fund managers typically stay (high turnover can be a red flag).
- Example: HDFC Mutual Fund and ICICI Prudential are well-established houses with decades of history and a wide range of funds that have weathered multiple market cycles — so an NFO from them carries some inherited credibility, even without its own history.
2. Fund Objectives
This is written in the Scheme Information Document (SID) — the legal offer document every NFO must publish.
- It spells out exactly what the fund will invest in: sector, market cap (large/mid/small), geography, asset allocation range, and strategy.
- Read this carefully rather than going by the fund’s catchy name — sometimes the name only tells part of the story.
- Example: The Kotak Global Tech Fund NFO’s objective was to invest in global technology companies. An investor should specifically check: which countries, how concentrated (top 10 holdings %), and whether it’s actively or passively (index-tracking) managed.
3. Risk Profile
Since there’s no historical NAV chart or return data to study, you’re relying purely on the category of risk the fund belongs to.
- Diversified/flexi-cap NFOs are generally lower risk than sector or thematic ones, because they aren’t tied to one industry’s fortunes.
- Sector-specific NFOs (energy, tech, infrastructure, pharma) can be volatile — if that one sector underperforms, the whole fund suffers, with no other sectors to cushion it.
- Rule of thumb: If you’re risk-averse, avoid sector/thematic NFOs entirely, and stick to diversified equity or hybrid fund NFOs (or skip the NFO altogether and wait for an existing fund with a track record).
4. Investment Horizon (Lock-in Periods)
Some NFOs aren’t as liquid as they seem.
- ELSS (Equity Linked Savings Scheme) NFOs come with a mandatory 3-year lock-in, since they qualify for tax deduction under Section 80C — you cannot redeem before 3 years, no matter what.
- Close-ended NFOs (sometimes thematic or FMP-style) may lock you in for the full tenure (3, 5, or even 10 years), with exit only via the stock exchange (often at a discount to NAV due to low trading volumes).
- Before investing, always check: is this open-ended or close-ended, and is there a lock-in? Match this against your need for liquidity.
5. Minimum Subscription Amount
- Most NFOs set a minimum lump-sum investment somewhere in the ₹500–₹5,000 range, making them accessible to most retail investors.
- Many NFOs also accept SIPs (Systematic Investment Plans) from the start — so instead of committing a lump sum during the offer window, you can start with smaller monthly investments even during/after the NFO period.
- This is worth checking specifically, since SIP availability and minimum SIP amounts can vary by fund house.
6. Costs (Expense Ratio)
- The expense ratio is the annual fee (as a % of your investment) the fund charges to manage your money — it directly eats into your returns.
- SEBI caps this: for equity funds, the Total Expense Ratio (TER) ceiling is 2.25% (this cap actually reduces in slabs as the fund’s AUM grows larger — the 2.25% is the upper limit for smaller equity fund sizes).
- Direct plans have a noticeably lower expense ratio than regular plans (no distributor commission), which compounds meaningfully over long horizons.
- Always compare the NFO’s proposed expense ratio to similar existing funds in the same category — an unusually high one is a caution sign.
7. Does the Theme Match Your Outlook?
This is the more subjective, “gut-check” factor — beyond the checklist.
- A thematic/sector NFO is essentially a bet: it only makes sense if you believe in that theme’s growth over the coming years.
- Example: If you believe India’s infrastructure sector (roads, power, ports, construction) is poised for strong growth over the next decade, an NFO like the HDFC Infrastructure Fund aligns with that conviction. But if you don’t have that specific view, there’s little reason to take on the concentrated risk of a sector fund — you’d be better off in a diversified fund.
2.4 Disadvantages Of Investing In NFO
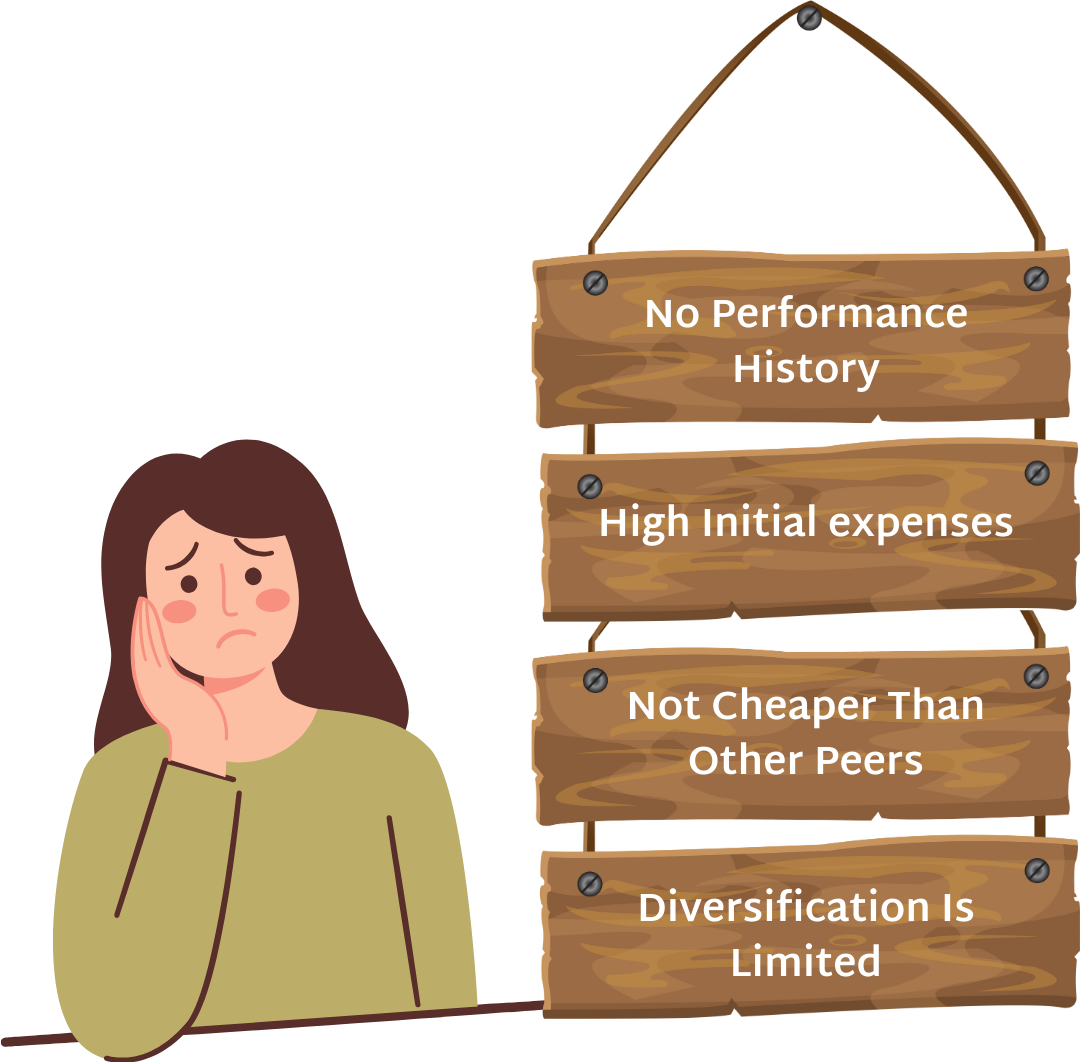
Anand: So NFOs have no upside to them then ?
Ridhima: There are definitely a few disadvantages to investing in a NFO that we need to weigh against the advantage of a shiny new theme. Let me go through them.
Disadvantages of NFOs
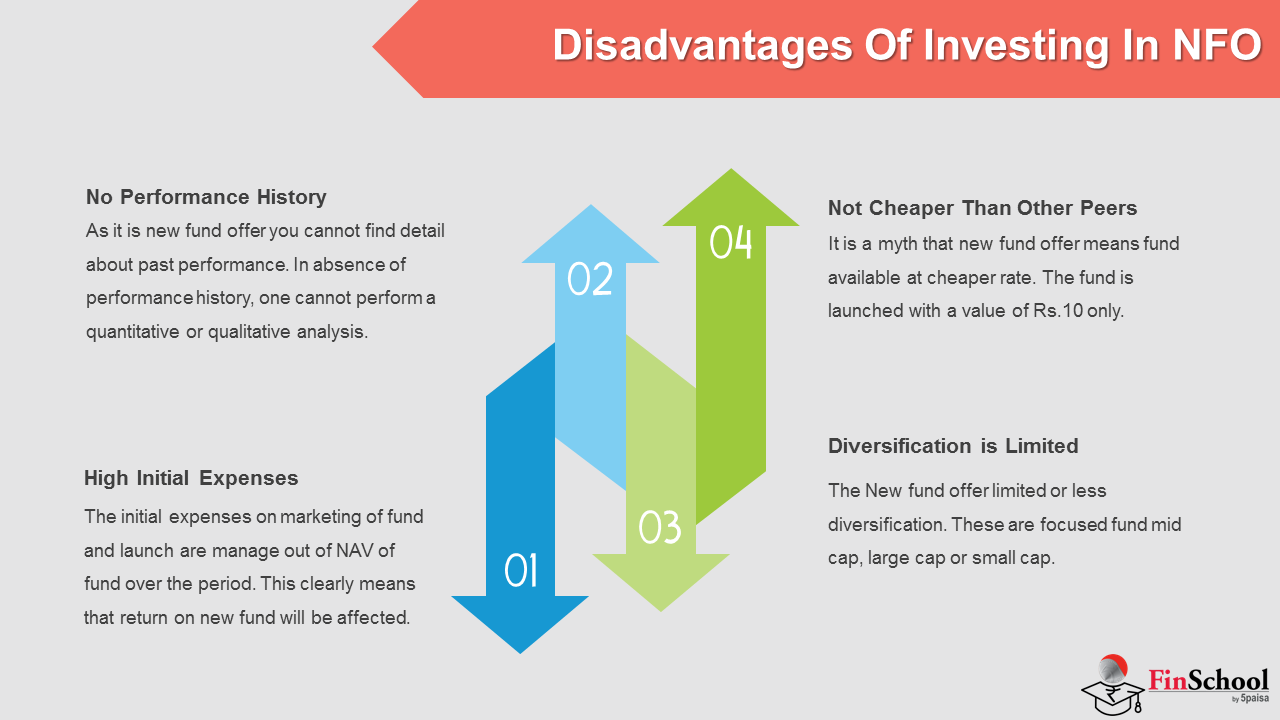
1. No Track Record : For an existing fund, we can look at 3 year / 5 year / 10 year returns, see how it weathered the storm in 2020 or in 2008, analyze the consistency of the fund manager. None of that is available to us for a NFO. And you are taking on the gamble of the fund manager’s ideology without knowing his track record in implementing it. Remember even the best fund house can have a badly performing scheme.
2. High initial costs : There are various costs that go into launching a new scheme such as advertising and distribution costs, agent costs, registrar costs, administrative costs etc. Which normally get loaded on to the scheme (within certain limits set by SEBI). This is in contrast to an existing scheme where these costs would already be borne by the Asset Management Company (AMC) and therefore not reflected in the NAV of the scheme currently. This means that when you invest in a NFO, until the costs are recovered (which may take some time), the returns would lag compared to an existing scheme.
3. Not cheaper: One of the biggest misconceptions about NFOs that first time investors have is that as the NAV of the NFO is say 10 Rupees compared to an existing scheme of say 85 Rupees, it provides much more value for money. However, the NAV of a scheme is purely indicative of the number of units outstanding in the market and does not reflect any value for money or risk adjusted returns. So in essence a 10 Rupee versus an 85 Rupee scheme, will have similar returns (in absolute terms and percentage terms) if they were to have invested in the same market scenario. It is what is inside the portfolio that determines returns and not the starting price point.
4. Less diversification : Many NFOs are launched with a very specific theme to them which makes them stand out from the crowd of existing schemes in the market. For example EV funds, Energy transition funds, small cap funds, global tech funds etc. While this gives the scheme an edge if the theme plays out well, it also presents a weakness if the theme doesn’t play out as expected.
The lack of diversification within the fund could mean that there is no hedge against market fluctuations in a certain segment or market cap. As an example, a small cap NFO has to invest only in small caps. If the small cap segment underperforms consistently for a few years (as it is known to do), the scheme does not have any diversification to protect against it.
2.5 Offer Document
Anand: How can I know all the details about an NFO ?
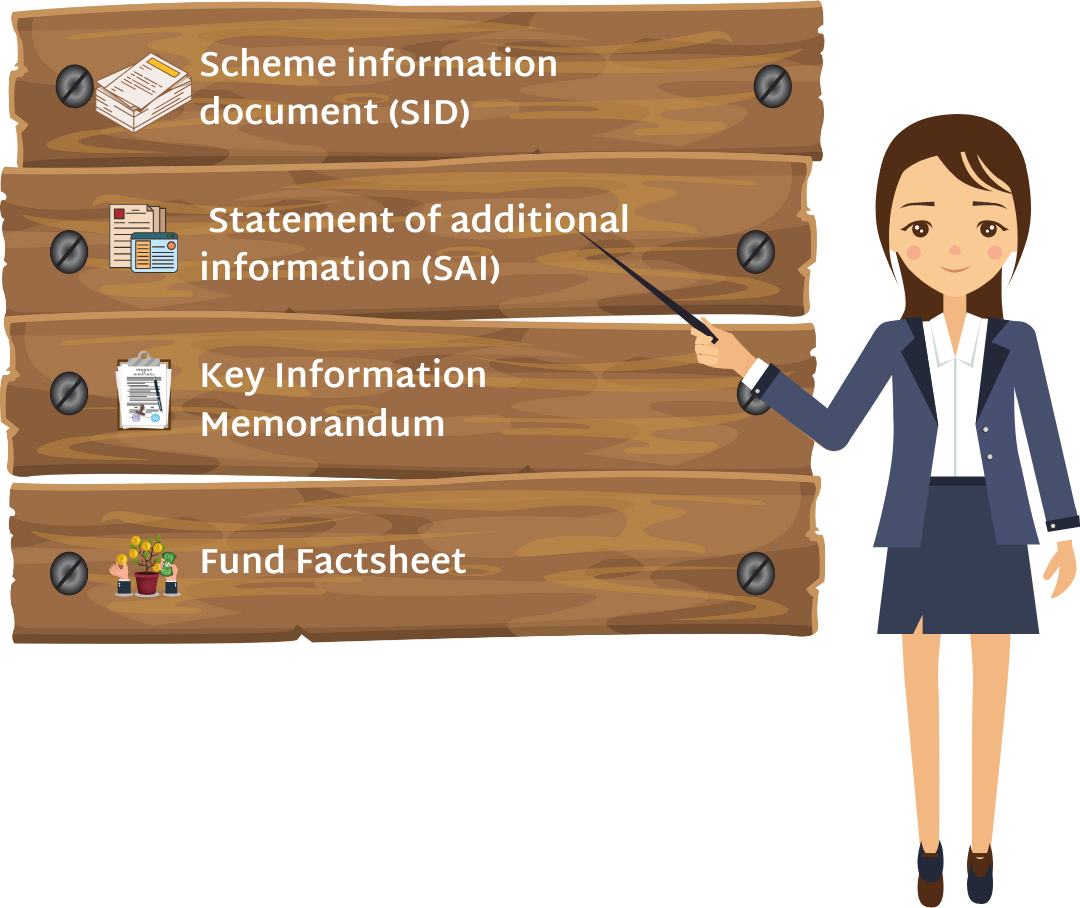
Ridhima: Well, you can find them in the offer documents. There are four categories of offer documents that we need to look at.
The Four Offer Documents
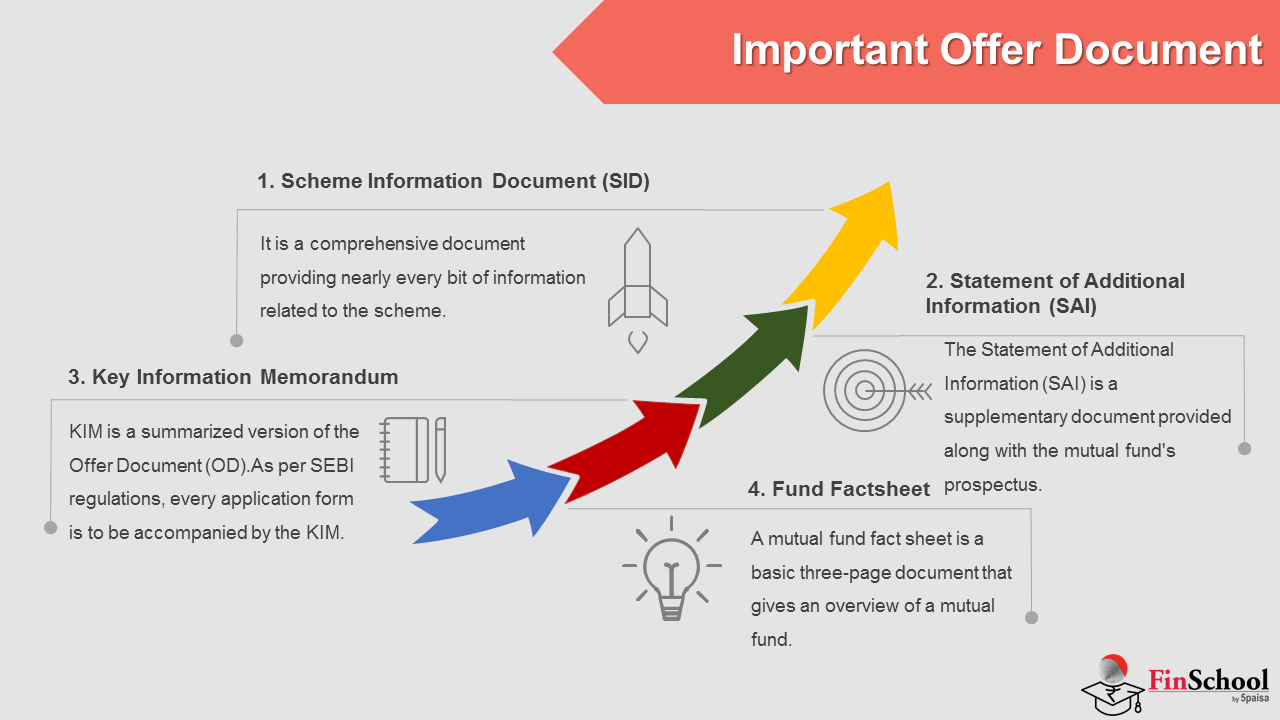
1. Scheme Information Document (SID): This is the largest document of them all and basically acts as the constitution of the scheme. It contains details such as investment objective of the scheme, allocation pattern (65-100% equity for instance or 0-35% debt), the theme and strategy that will be used within the scheme, the index to which it will be benchmarked, the fund manager, risk factors specific to the scheme, load structure (charges for entering and exiting the fund), minimum investment to open a folio etc. It is this document that you need to read if you want to know what the scheme will do with your money (objectives) and how it will do it (strategy).
2. Statement of Additional Information (SAI) : This is a very detailed document (but less interesting for the average investor) which pertains to all schemes of an AMC (and not a specific scheme). It contains information such as taxation implications, computation of NAV, rights of shareholders, the constitution of AMC, trustees, sponsors etc. Most retail investors would not read this document end to end, however it can prove a useful resource if you are interested in the nitty gritty of how the fund is taxed or how its NAV is calculated.
3. Key Information Memorandum (KIM)
It is a summary of the SID in a much more easily digestible format (and hence the name) and is meant to be given to / made available to investors at the time of investing (in other words, this is what you will sign on the dotted line). It contains key facts such as the objective of the fund, allocation pattern, risk factors, the fund manager, minimum investment, load structure and the procedure to apply.
4. Fund Factsheet
This factsheet is published every month (and not at the time of launch of the NFO) and contains information such as NAV, AUM, Expense Ratio, portfolio (top stocks and sectors held by the fund), allocation pattern, risk measures (standard deviation, beta, sharpe ratio) and returns compared to the benchmark. Once the NFO period is over, this factsheet becomes your companion document to keep track of not only the returns that the fund is posting but also where your money is invested.